Real Estate in Lagos Nigeria
Buying property can be an important financial decision, particularly in a busy market such as Lagos. From residential houses and apartments to commercial buildings and undeveloped land, the real estate market in Lagos Nigeria offers different opportunities for home buyers and investors. However, choosing a suitable property requires more than comparing prices or selecting a preferred neighbourhood. Buyers must understand ownership documentation, location, infrastructure, additional expenses and the risks associated with property transactions. A property that appears attractive online may have legal, structural or financial issues that are not immediately obvious. Understanding these factors before making a commitment can help buyers make informed decisions and reduce avoidable losses.
1. Understand the Lagos Real Estate Market
The Lagos property market includes several segments, each serving different needs and budgets. Residential properties include apartments, detached houses, terraced houses and duplexes. Commercial properties include offices, retail spaces, warehouses and other premises used for business activities. Land purchases also attract buyers who intend to build homes, develop commercial projects or hold land for potential future appreciation. Each segment has different ownership considerations, costs and risks. Before beginning a search, determine whether you need a home to live in, a property to rent out, a business location or land for future development. This decision will help you focus your research on relevant property types.
Demand, infrastructure, accessibility and economic activity can influence property values across Lagos. Areas with convenient transport connections, established services and access to employment or commercial centres may attract substantial buyer interest. However, high demand does not automatically make every property a good investment. Buyers should investigate the actual conditions of a location, including road access, drainage, electricity, security and nearby amenities. They should also compare properties with similar characteristics rather than assuming that all properties in the same neighbourhood have equivalent value. Researching the local market provides a stronger basis for judging whether the asking price and property features match your needs and financial capacity.
2. Choose the Right Location for Your Needs
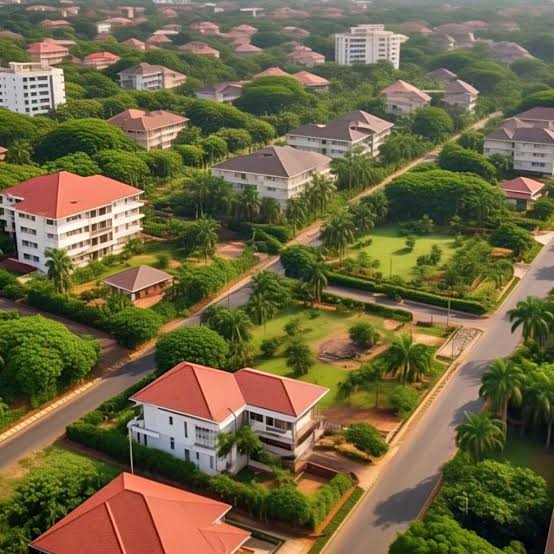
Location affects daily convenience, property costs and the potential usefulness of a property over time. Buyers working in central business districts may prioritise transport access and commuting time, while families may place greater importance on schools, healthcare facilities, shopping areas and residential surroundings. Business owners may need proximity to customers, suppliers and major roads. These requirements should guide the selection process instead of relying entirely on a neighbourhood’s popularity. A real estate in Lagos Nigeria that meets your practical needs may offer better long term value than a more expensive alternative that creates daily transport difficulties or requires additional spending to make the location convenient.
Before making an offer, visit the neighbourhood and assess it at different times of the day where practical. Observe traffic conditions, road quality, drainage, noise, street lighting and the availability of essential services. Ask residents or other reliable local sources about recurring problems, including flooding, access restrictions and infrastructure disruptions. Also consider whether the surrounding environment is suitable for your intended use. A property may look impressive during a brief inspection but become less attractive after its wider surroundings are assessed. Comparing several locations using the same criteria helps you identify meaningful differences and avoid decisions based solely on photographs, sales descriptions or verbal assurances.
3. Verify Property Documents Before Paying
Property verification is one of the most important stages of buying real estate in Lagos Nigeria. A seller’s claim of ownership should not be treated as sufficient evidence that the transaction is legally secure. Depending on the property and its history, relevant documents may include a registered survey plan, deed of assignment, Certificate of Occupancy, evidence of an applicable government consent, or documents relating to the property’s allocation and acquisition history. Not every property will have the same documentation, and the presence of a particular document does not automatically establish that the title is free from defects. The documents must be assessed in the context of the specific transaction.
Engage an independent property lawyer to investigate the title and confirm the appropriate verification process with the relevant land registry and government authorities. The checks should establish whether the seller has the legal capacity to transfer the interest being sold and whether there are registered interests, disputes, restrictions or acquisition issues affecting the property. For land, survey information should also be examined to establish the location and boundaries and to identify possible overlaps or encroachments. Where applicable, planning and land use requirements should be checked before assuming that the property can be developed for a particular purpose. Avoid relying solely on documents supplied by the seller or an intermediary.
Never rush into payment because a seller claims that another buyer is ready to complete the transaction. Confirm the agreed terms, the parties’ identities, the property’s description and the payment arrangements before transferring substantial funds. Keep copies of receipts, agreements, correspondence and other transaction records. Where a deposit is proposed, obtain independent legal advice about the conditions under which it is paid and whether it can be refunded. Buyers should also establish what costs and obligations remain after the initial payment, including registration, consent or perfection requirements where applicable. Careful documentation and professional verification help reduce the risk of disputes, fraudulent transactions and unexpected legal expenses.
4. Calculate the Full Cost of Buying Property
The advertised price is not necessarily the total amount required to purchase and secure a property. Buyers may need to budget for legal services, valuation, survey work, agency fees, title investigation, applicable taxes, registration and other transaction related expenses. The actual costs depend on the property, the parties’ agreement and the applicable legal and administrative requirements. Some properties may also require outstanding charges to be resolved before the transaction can proceed. Request a written breakdown of expected expenses and confirm which party is responsible for each item. This makes it easier to compare properties on their total cost rather than their asking prices alone.
The financial assessment should continue beyond the purchase itself. A house may require repairs, renovation, furnishing, security improvements or utility connections before it becomes suitable for occupation. Land buyers should investigate the cost of preparing the site, obtaining necessary approvals and carrying out construction if development is intended. Investors purchasing rental property should consider periods without tenants, maintenance, insurance where appropriate, management expenses and the possibility of delayed rental payments. These costs can affect the property’s overall financial performance. Prepare a realistic budget that includes a contingency for unexpected expenses, and avoid committing all available funds to the purchase price without considering the costs that follow.
5. Inspect the Property and Its Physical Condition
A property inspection helps buyers identify visible defects and determine whether further professional assessment is necessary. Examine walls, ceilings, floors, windows, doors, plumbing, electrical installations and signs of water penetration. Pay attention to cracks, dampness, poor ventilation, damaged fittings and evidence of previous repairs that may conceal underlying problems. For older buildings or properties with significant defects, consider engaging a qualified building professional to assess the condition and likely repair requirements. Photographs and written inspection notes can help you compare properties objectively. Do not assume that a recently painted building or attractive interior necessarily indicates that the property is structurally sound or well maintained.
The surrounding infrastructure also deserves attention. Check the accessibility of the property, the condition of access roads, drainage arrangements, water supply and available electricity connections. Where flooding is a concern, investigate the area’s history and inspect drainage conditions instead of relying on assurances from a seller. For undeveloped land, confirm the boundaries and assess the terrain, access rights and suitability for the intended development. Buyers should also determine whether the proposed use complies with relevant planning rules and approvals. A property that requires substantial corrective work may still be suitable, but the likely costs and practical limitations should be understood before the purchase price is agreed.
6. Compare Prices and Research Market Value
Comparing similar properties is more useful than judging a purchase by a single asking price. Review properties in the same neighbourhood or in locations with comparable accessibility, infrastructure and services. Consider the property type, land size, building condition, age, title status and facilities included in the transaction. Asking prices represent what sellers hope to receive, not necessarily the final prices paid by buyers. Where reliable transaction information is available, it can provide a better basis for assessing value. Property agents, valuers and other qualified professionals may help explain local price differences, but their claims should be supported by relevant evidence where possible.
Buyers should be cautious about assuming that a property will automatically appreciate because it is located in a popular area. Future values may be affected by economic conditions, infrastructure delivery, neighbourhood changes, supply, demand and the property’s legal or physical condition. An investment assessment should therefore consider several possible outcomes rather than relying on an optimistic forecast. For a rental property, estimate realistic rental income and deduct likely operating expenses before evaluating potential returns. For a home, consider affordability and long term suitability alongside resale prospects. This approach supports more balanced decisions and helps buyers distinguish between an attractive sales pitch and an opportunity that fits their circumstances.
7. Understand the Roles of Agents and Other Professionals
Real estate agents can help buyers discover available properties, arrange inspections, communicate with sellers and understand local market conditions. However, buyers should establish an agent’s identity, professional standing, role in the transaction and fee arrangements before proceeding. Ask who the agent represents, whether other parties are involved and how any commission is calculated. A property listing or recommendation from an intermediary should be treated as a starting point for independent checks, not proof of ownership or a guarantee that a property is suitable. Clear communication helps prevent misunderstandings about the price, included features, payment deadlines and responsibilities of each party.
Different professionals may be needed at different stages of a purchase. A property lawyer can advise on title and contractual issues, while a qualified surveyor can assist with boundaries and survey matters. A building professional may assess structural or maintenance concerns, and a valuer can provide an independent opinion of market value for an appropriate purpose. Buyers should select professionals whose expertise matches the task and avoid allowing one interested party to control every stage of verification. Professional fees should be understood before work begins. Independent advice may add to the upfront cost, but it can help identify issues that would otherwise result in substantial financial or legal difficulties.
8. Check Planning Requirements and Future Development
A property’s current appearance does not establish that every proposed use or future development will be permitted. Buyers intending to construct a house, extend a building, operate a business or redevelop a site should investigate the relevant planning rules, land use designation and approval requirements. Existing buildings may also have alterations or additions that require verification. Consult the appropriate planning authority and qualified professionals before assuming that a particular development is allowed. For commercial properties, consider whether the premises are suitable for the intended activity and whether additional approvals or compliance requirements may apply. These checks are especially important when the purchase depends on a planned development or change of use.
Future infrastructure and neighbourhood development can affect a property’s convenience and attractiveness, but proposed projects should not be treated as guaranteed benefits. Confirm announcements through reliable official sources and distinguish funded or ongoing projects from unverified claims. Also investigate potential disadvantages, such as construction disruption, changing traffic patterns, drainage concerns or restrictions affecting access. For land purchases, ensure that the site can reasonably accommodate the intended project and that the necessary approvals can be pursued. Evaluating both the opportunities and limitations of an area provides a more balanced picture than relying on promises of rapid appreciation or claims that a location is certain to become the next major property hot spot.
9. Match the Property to Your Financial Goals
The right property depends on why you are buying and what you can realistically afford. A first time home buyer may prioritise affordability, safety, access to work and space for household needs. A landlord may focus on tenant demand, maintenance requirements, likely rental income and the cost of managing the property. A business owner may need visibility, customer access, parking or storage facilities. Land investors may be more concerned with title security, development potential, holding costs and the period for which they can leave the investment untouched. Defining your priorities before viewing properties helps you avoid spending time on options that do not match your needs.
Prepare a financial plan that accounts for your available funds, borrowing obligations where relevant, recurring expenses and emergency reserves. If you are relying on rental income or future resale to make the purchase financially viable, examine how the property would perform if income were lower than expected or the sale took longer than planned. Avoid assuming that property ownership guarantees immediate profit or a steady return. Compare the purchase with other uses of your money and consider whether the investment period suits your financial circumstances. A well chosen property should meet a clear purpose without creating unsustainable financial pressure.
10. Complete the Transaction Carefully
Before completing the purchase, review the sale agreement with your lawyer and confirm that the agreed price, payment schedule, property description, completion conditions and responsibilities of the parties are clearly documented. Resolve outstanding questions about possession, keys, fixtures, unpaid charges and any obligations that must be fulfilled before or after completion. Confirm that the person receiving payment is authorised to do so and retain appropriate evidence of every transaction. The completion process should follow the legal requirements applicable to the property and the nature of the interest being transferred. Avoid making major payments based only on verbal promises, informal messages or pressure from an intermediary.
After completion, keep the original documents and transaction records securely, follow up on any remaining registration or consent requirements and confirm that the property has been handed over according to the agreement. Owners should also retain inspection reports, approved plans and relevant maintenance records where applicable. If the property will be rented out, establish clear tenancy arrangements and a plan for repairs, record keeping and communication with tenants. For buyers who intend to develop land, seek the necessary professional advice and approvals before construction begins. Treating completion as a documented process, rather than simply the final payment, helps protect the value and practical use of the property.
Conclusion
Buying real estate in Lagos Nigeria requires careful research, financial preparation and independent verification. Understanding the market, selecting an appropriate location, checking title documents, calculating the full cost and inspecting the property’s condition are essential steps. Buyers should also compare market values, verify the roles of intermediaries, investigate planning requirements and match each purchase to their financial goals. No checklist can eliminate every property risk, but a structured decision making process can help identify problems before they become expensive. Before committing funds, consult qualified professionals who can assess the specific property and transaction. The objective is not simply to find an attractive listing, but to make a well informed purchase that meets your needs and budget.